India’s NBFC sector is scaling faster than the infrastructure most institutions run on. As loan books grow, branches multiply, and regulatory scrutiny tightens, spreadsheets and disconnected tools simply can’t keep up. This is where non banking financial software comes in purpose built technology designed to run every part of an NBFC’s operations, from loan origination to compliance reporting, on a single connected platform.
In this guide, we’ll break down what non banking software actually does, why cloud nbfc software is becoming the industry standard, and how to evaluate Non Banking Software Solutions so you can pick a platform that scales with your business instead of holding it back.
What is Non Banking Financial Software? (And Why It’s the Backbone of Modern NBFCs)
Non banking financial software is a category of enterprise technology built specifically for Non Banking Financial Companies institutions that offer loans, credit, and financial services without holding a full banking license. Unlike generic business software, it’s designed around the specific workflows NBFCs run every day: loan origination, disbursement, collections, credit assessment, and regulatory filing.
At its core, good non banking software does three things exceptionally well: it speeds up operations, reduces manual error, and keeps the institution audit ready at all times. For an industry where margins are tight and compliance requirements are strict, that combination isn’t optional, it’s existential.
Core Modules Inside Non Banking Software Solutions
- Most comprehensive Non Banking Software Solutions bundle together the following capabilities:
- Loan origination and underwriting: digital application intake, credit scoring, and automated approval workflows.
- Loan servicing and collections: EMI tracking, repayment scheduling, and automated reminders.
- Customer relationship management: a built in CRM software layer for managing leads, borrower communication, and retention.
- Compliance and regulatory reporting: automated filings aligned with RBI norms.
- Accounting and financial management: general ledger integration, treasury tools, and MIS reporting.
- Product specific modules: including gold loan software for collateral backed lending and microfinance software for group and small ticket loans.
Rather than stitching together five or six disconnected tools, a unified non banking financial software platform lets every department credit, operations, collections, and compliance work from the same real time data.
This matters more than it might first appear. When credit, collections, and compliance teams each work from a different system, small inconsistencies, a missed payment update, an outdated KYC record, a delayed compliance flag compound into real operational risk. A single, well architected platform closes those gaps by design, not by policy.
Why NBFCs Are Shifting to Cloud NBFC Software in 2026
For years, NBFCs ran on premise servers because that’s what banking adjacent institutions were expected to do. That’s changing fast. Cloud nbfc software has moved from a nice to have to the default choice for NBFCs that want to launch new branches quickly, control IT costs, and stay resilient against outages or disasters.
5 Real Benefits of Cloud NBFC Software
- Switching to cloud nbfc software delivers measurable advantages over legacy on premise systems:
- Faster branch rollouts and new locations can go live in days instead of months, since there’s no server hardware to install.
- Lower total cost of ownership subscription based pricing removes the need for large upfront infrastructure investment.
- Automatic updates and patches compliance and feature updates roll out centrally, with zero downtime for branch staff.
- Real time visibility across branches leadership can monitor loan books, collections, and risk exposure from anywhere.
- Built in disaster recovery data backups and failover systems protect the business against hardware failure or local outages.
Is Cloud NBFC Software Secure Enough for Financial Data?
This is the question every CFO and compliance officer asks before migrating. The honest answer: reputable cloud nbfc software providers typically offer stronger security than most in house server setups, using bank grade encryption, multi factor authentication, role based access controls, and continuous security monitoring. Combined with regular third party audits, cloud platforms often close security gaps that aging on premise infrastructure never addressed in the first place.
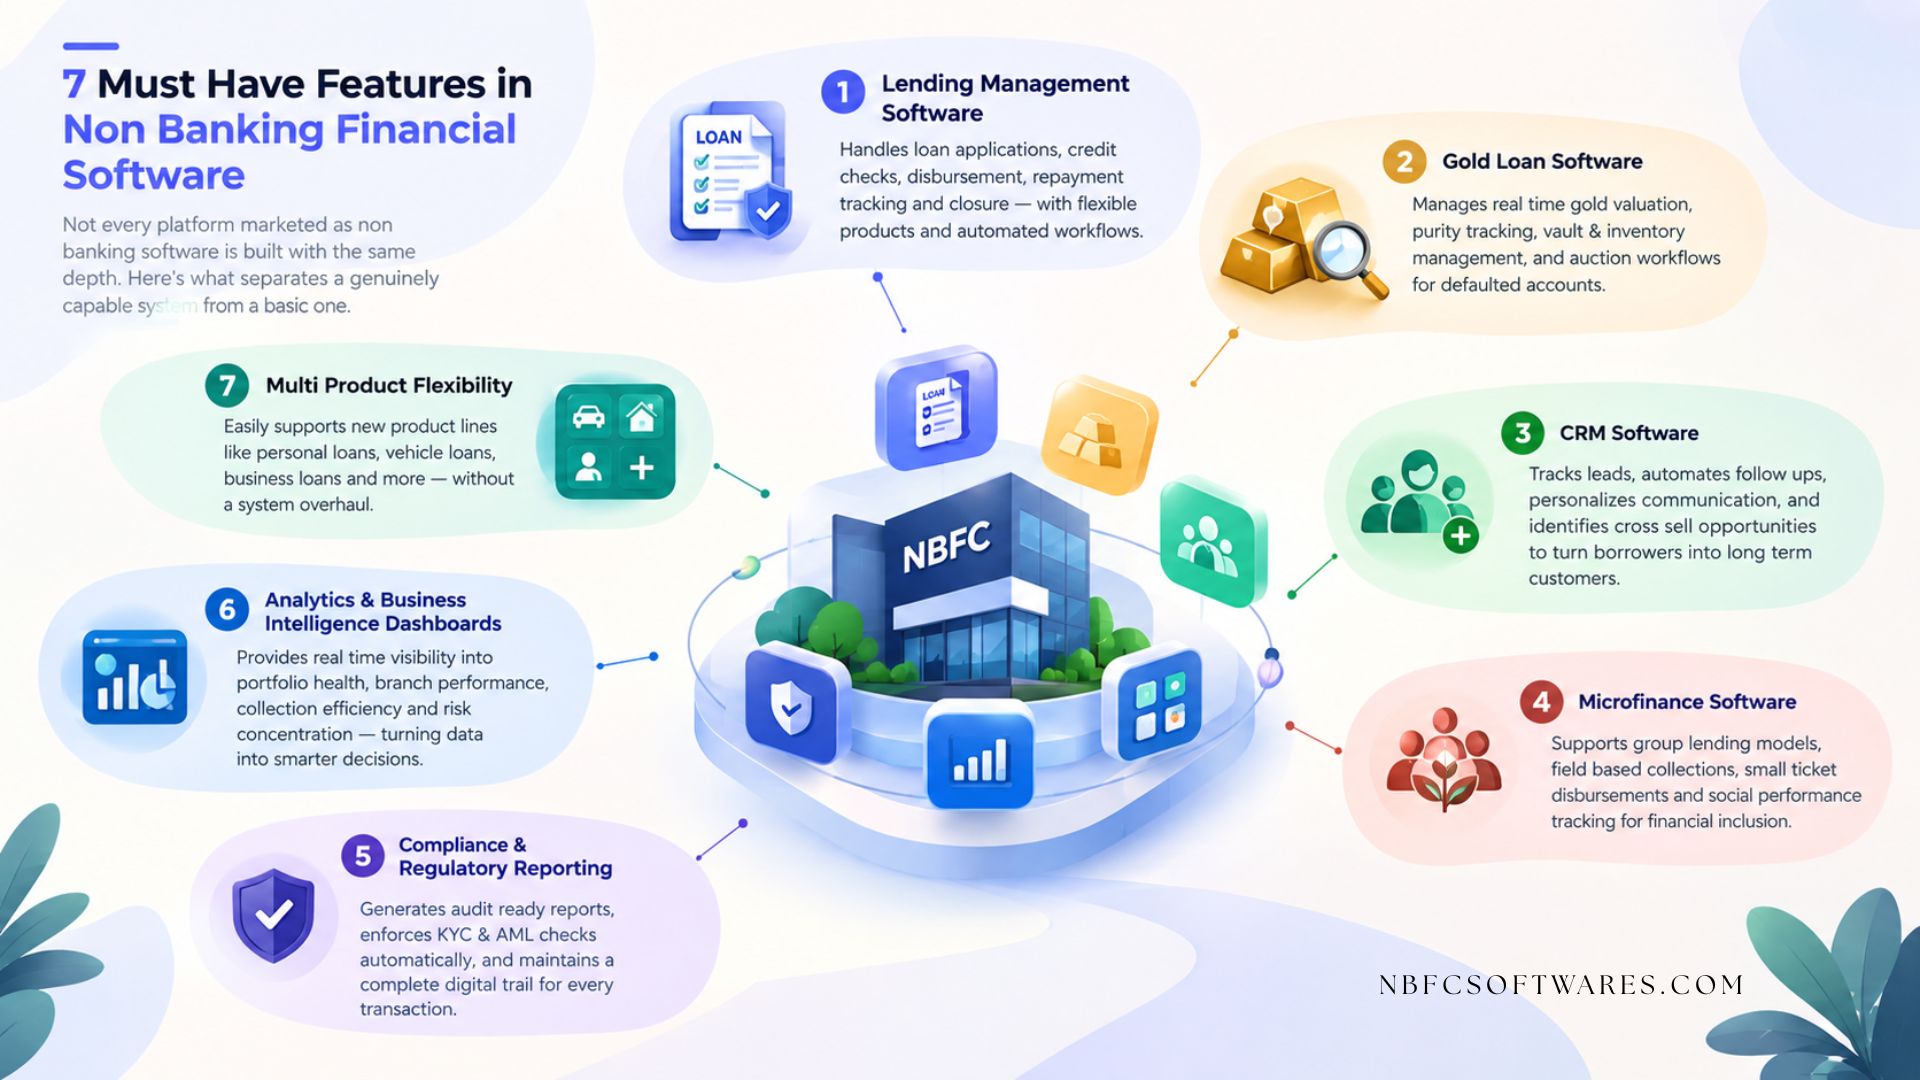
7 Must Have Features in Non Banking Financial Software
Not every platform marketed as non banking software is built with the same depth. Here’s what separates a genuinely capable system from a basic one.
Lending Management Software: The Engine Behind Loan Operations
At the heart of any NBFC platform is lending management software the engine that handles loan applications, credit checks, disbursement, repayment tracking, and closure. A strong lending engine should support configurable loan products, flexible interest structures, and automated workflows that reduce manual touchpoints at every stage of the loan lifecycle.
Gold Loan Software: Specialized Support for Collateral Backed Lending
If your NBFC offers gold backed loans, generic lending tools won’t cut it. Dedicated gold loan software handles real time gold valuation, purity tracking, vault and inventory management, and auction workflows for defaulted accounts features a standard lending module simply doesn’t include.
CRM Software: Turning Borrowers into Long Term Customers
Acquiring a borrower is only half the job, retaining them is what drives long term profitability. Inbuilt crm software capabilities help NBFCs track leads, automate follow ups, personalize communication, and identify cross sell opportunities, turning one time borrowers into repeat customers.
Microfinance Software: Serving the Underbanked at Scale
For NBFCs focused on financial inclusion, microfinance software supports group lending models, field based collections, small ticket disbursements, and social performance tracking workflows that look very different from traditional secured lending and need purpose built tools to manage well.
Compliance & Regulatory Reporting
Every NBFC operates under close regulatory oversight. The right non banking financial software should generate audit ready reports, enforce KYC and AML checks automatically, and maintain a complete digital trail for every transaction reducing both manual effort and regulatory risk.
Analytics & Business Intelligence Dashboards
Real time dashboards give management visibility into portfolio health, branch performance, collection efficiency, and risk concentration turning raw operational data into decisions leadership can act on immediately.
Multi Product Flexibility
As NBFCs diversify into new products personal loans, vehicle loans, business loans the software should support new product lines without requiring a system overhaul, protecting your original technology investment as the business grows.
Non Banking Software vs. Traditional Banking Software: What’s Different?
It’s a common misconception that NBFCs can simply repurpose banking software. In reality, non banking software is built around a fundamentally different regulatory and operational framework. NBFCs don’t accept public deposits the way banks do, follow a distinct set of RBI guidelines, and often operate leaner branch networks with faster loan turnaround expectations.
This means Non Banking Software Solutions are optimized for speed and flexibility, quicker underwriting cycles, simpler onboarding, and product specific modules like gold loan software or microfinance software rather than the broader, slower moving infrastructure built for full service banks.
How to Choose the Right Non Banking Software Solutions Provider
With no shortage of vendors claiming to offer the “best” platform, here’s a practical framework for separating serious providers from the rest.
7 Questions Every Smart NBFC Asks Before Signing
- Does the platform specialize in NBFC workflows, or is it a generic lending tool with NBFC features added on later?
- Is it built as cloud nbfc software, and does that match your IT strategy and budget?
- Does it include a genuine lending management software core, or just basic loan tracking?
- Are product specific modules available such as gold loan software or microfinance software if you need them?
- How strong is the built in crm software layer for managing borrower relationships long term?
- What does implementation and data migration actually involve?
- What ongoing support and training does the vendor provide after going live?
A trustworthy provider of Non Banking Software Solutions will walk you through these questions transparently and offer a live demo before asking for a long term commitment.
Common Mistakes NBFCs Make When Adopting New Software
Even strong platforms can underdeliver if the rollout isn’t handled carefully. Watch for these common missteps:
- Choosing based on price alone. The cheapest non banking financial software rarely includes the compliance depth or scalability a growing NBFC needs.
- Skipping proper data migration planning. Moving historical loan and customer records from legacy systems requires careful mapping and rushed migrations create data gaps.
- Underinvesting in staff training. Even intuitive non banking software needs hands on onboarding for credit, operations, and collections teams.
- Ignoring product specific needs. NBFCs offering gold loans or microfinance products need dedicated modules, not a one size fits all lending tool.
- Failing to plan for growth. Choosing rigid cloud nbfc software that can’t support new products or branches leads to a costly system change down the road.
5 Trends Shaping Non Banking Financial Software in 2026
The technology NBFCs rely on is evolving quickly, and staying current matters as much as choosing the right platform today. Keep an eye on these shifts:
- AI driven credit scoring. More non banking financial software platforms are embedding machine learning models that assess creditworthiness faster and more accurately than manual underwriting alone.
- Embedded lending partnerships. NBFCs are increasingly plugging their lending management software into e-commerce, fintech, and retail platforms to offer credit at the point of sale.
- API first architecture. Modern Non Banking Software Solutions are built to integrate easily with credit bureaus, payment gateways, and third party fintech tools rather than operating as closed systems.
- Deeper regulatory automation. As RBI reporting requirements grow more granular, non banking software is taking on more of the compliance burden automatically, rather than relying on manual report generation.
- Unified multi product platforms. Instead of running separate systems for gold loan software, microfinance software, and unsecured lending, NBFCs are consolidating everything into one cloud nbfc software platform for a single source of truth.
Choosing a vendor that’s actively investing in these areas rather than one that hasn’t meaningfully updated its platform in years will matter more with every passing budget cycle.
The ROI of Investing in the Right Non Banking Financial Software
Cost is always a factor in any technology decision, but the more useful question is what return the investment generates. NBFCs that move from manual or fragmented systems to a unified non banking financial software platform typically see improvements across several areas:
- Faster loan turnaround times, since underwriting, approval, and disbursement happen on one connected workflow instead of across disconnected tools
- Lower operational costs, as automation reduces the manual work required for data entry, reconciliation, and reporting
- Fewer compliance penalties, thanks to built in regulatory checks and audit ready reporting
- Higher borrower retention, driven by the built in crm software layer that keeps communication consistent and timely
- Easier scaling, since cloud nbfc software lets new branches and products launch without major new infrastructure spend
For most NBFCs, these gains compound quickly enough that the software pays for itself well within the first operating cycle making the real question not whether to invest, but which Non Banking Software Solutions provider to invest in.
FAQ’s
What’s the difference between non banking financial software and core banking software?
Non banking software is purpose built for NBFC specific workflows and regulations, while core banking software is designed for deposit taking institutions with broader compliance requirements.
Is cloud nbfc software suitable for small and mid sized NBFCs?
Yes in fact, cloud nbfc software is often the better fit for smaller NBFCs, since it removes the need for costly inhouse infrastructure and scales as the business grows.
Can one platform handle both gold loans and microfinance products?
Many modern Non Banking Software Solutions combine gold loan software and microfinance software capabilities into a single multi product platform, giving NBFCs a unified view of a diversified loan book.
Does non banking financial software include CRM capabilities?
Leading platforms include an inbuilt CRM software layer for lead tracking, borrower communication, and retention, eliminating the need for a separate standalone CRM tool.
How long does implementation typically take?
Cloud based non banking financial software generally deploys faster than on premise systems, since there’s no physical infrastructure to install branch by branch.
What should a first time buyer prioritize when comparing vendors?
Beyond price, prioritize how well the non banking software fits your specific loan products, how transparent the vendor is about implementation timelines, and whether they offer a live demo so your team can test real workflows before committing.
The Bottom Line: Build a Future Ready NBFC with the Right Software
The NBFCs that will lead India’s lending market over the next decade are the ones investing today in technology built for how they actually operate. Whether it’s a robust lending management software core, specialized gold loan software, borrower focused crm software, or inclusion driven microfinance software, the right non banking financial software platform brings every function of the business onto one connected, compliant, and scalable system.
As you evaluate Non Banking Software Solutions, prioritize providers offering genuine cloud nbfc software, transparent pricing, and a live demo so you can see exactly how the platform performs before making a long term commitment. Get this decision right, and your technology stops being a constraint and starts becoming your NBFC’s biggest competitive advantage.